All over the world, online marketplaces totaled more than 3 trillion dollars worth of sales in 2021. The top 100 online marketplaces are primarily concentrated in North America, Europe, Asia, and Latin America. The Middle East/Africa region is steadily catching up.
Even better, the e-commerce share of total retail sales around the globe was expected to increase to almost 25% by 2025, with more than 2 billion people shopping online. Yclas believes in the transformative power of e-commerce.
In short
- Yclas supports dozens of payment gateways. This guide covers ten: Stripe, PayPal, 2Checkout, Escrow.com, BitPay, Robokassa, Mercado Pago, Alipay (through Stripe), Authorize.net and SecurePay.
- On a $100 sale, Stripe and Authorize.net cost $3.20, PayPal $3.98, 2Checkout $3.85, BitPay $2.25 and Escrow.com its $50 minimum.
- Fixed fees hurt small payments: PayPal takes about 13% of a $5 featured upgrade, so sell bundles or monthly seller plans instead.
- Stripe Connect on Yclas gives sellers Express accounts, an optional escrow flow and per-plan commissions, but set your commission well above the 2.9% plus 30 cents card rate.
- Use the gateway's hosted checkout so card numbers never touch your server (PCI DSS v4.0.1), and offer a second gateway in case one account is frozen.
Part of the guide Making money from your marketplace
Why a Good Payment Gateway is Vital for Your Online Marketplace
Every year, about 32.4% of hacking attempts are successful. And often, hackers target e-commerce websites through financial fraud, phishing, spamming, DoS and DDoS attacks.
A good payment gateway helps protect sensitive details like credit card numbers by encrypting the payment information.
A secure and efficient payment gateway ensures a successful online marketplace website.
- 15% of shoppers will abandon a cart if they don't think they have a good experience
- 6% of them will seek a shop with better payment options
- 4% will leave a website if it's having technical issues with its payment
The Baymard Institute puts the average documented cart abandonment rate at 70.22%, calculated from 50 studies. In its survey, 19% of shoppers who abandoned a cart did not trust the site with their card details, 10% had a card declined and 9% said there were not enough payment methods.
Let's explore ten great payment options Yclas offers to get you processing payments.
Stripe's Leading Market Share for Payment Processing
Launched in 2010, Stripe is a payment processor that accepts more than 135 currencies and payment methods, including credit and debit cards, mobile wallets and buy now, pay later services. Stripe is used in 46 countries and was valued at $94.4 billion in 2021.
3.1 million websites use Stripe, and according to its website, the gateway receives more than 250M API requests daily. Currently, Stripe has 48 patents and 39 investors, including Elon Musk. It holds more than 15% of the market share in the payment processing industry.
PayPal's Trusted Security
 PayPal rose to worldwide popularity after eBay acquired it for 1.5 billion dollars back in 2002. Since then, it has become the most used digital payment method globally, with a reported base of 392 million active users in 2021.
More than 1.6 million websites use PayPal, and buyers are reportedly 54% more willing to buy from a store if it accepts PayPal. In 2020 alone, this payment gateway processed more than 15 billion transactions; in 2021, it generated an annual total payment value of 936 billion dollars.
Like Stripe, PayPal employs protective mechanisms to secure customers' account information, such as transaction monitoring and anti-fraud systems.
2Checkout's Payment Gateway Flexibility
Officially started in 2006, 2Checkout was founded by the people who developed RAV Antivirus, a piece of technology that Microsoft purchased to form part of its antivirus software offerings. In 2020, Verifone acquired it and envisioned a platform that would "enable omnichannel commerce wherever and whenever clients shop."
Pioneering cashless payment, 2Checkout has an estimated annual revenue of $30.1M, with more than 400,000 users worldwide. According to its website, the gateway processes 10.3 billion transactions yearly, with over 80 global offices.
Pioneering cashless payment, 2Checkout has an estimated annual revenue of $30.1M, with more than 400,000 users worldwide.
As a complete e-commerce solution, it offers various programs for online sellers. Its most expensive option, for instance, allows you to sell in 200 countries or territories and integrate with 120+ carts.
Its most affordable plan still offers good value, with access to more than 45 payment methods, conversion rate optimization, and shopping cart customization.
Escrow.com's Simplicity in Online Marketplace Payment Processing
 Founded in 1999, Escrow.com is an online escrow processing payment gateway that offers the "simplest way" to complete escrow transactions. Integrating with your marketplace website is easy, as it only requires one API call.
Additionally, it accepts various types of payment methods, such as PayPal, bank debit, wire transfer, or credit and debit cards. Since it was acquired by Freelancer.com back in 2015, it has won numerous awards.
These include a Gold award for Company of the Year in the Small Financial Services sector from The International Business Awards. Escrow.com also won the BBB Torch Award for Ethics from the Better Business Bureau. Escrow.com is used by several trusted e-commerce websites such as Shopify Exchange and GoDaddy.
BitPay for Processing Bitcoin Payments
If you want to enable Bitcoin payments through your website, BitPay will allow you to do this. Established in 2011, it has since developed into the leading provider of blockchain payment technology that offers "powerful, enterprise-grade tools for crypto acceptance and spending." In 2022, BitPay was set to process more than 70,000 transactions every month.
Customers can buy a cryptocurrency with their credit or debit cards or use their crypto and convert it into dollars through the BitPay card. The top industries that use this payment gateway are computers, electronics, technologies, law and government, and finance.
Robokassa for a Russian Online Marketplace
Robokassa is an online payment gateway for the Russian market, so if your online marketplace website is targeting this market, Robokassa is one to consider. This platform was founded in 2002 and has gathered more than 202,000 active users.
As a comprehensive solution, it accepts several popular payment methods, including online wallets, banking cards, installment cards, and Yandex contactless payment. It also offers Robocheki, an online tool that enables accepting payments without a cash register.
Mercado Pago for Latin American Online Marketplaces
On the other side of the world, Yclas' integration with Mercado Pago makes it easy for marketplace website entrepreneurs in Latin America to process payments. Created by Mercado Libre, the largest e-commerce ecosystem in the region, the platform reportedly processed more than 3 billion transactions in 2021, up by about 70% from the number of transactions it facilitated in 2020.
The platform reported processing more than 3 billion transactions.
Around 20 million people in Mexico, Argentina, and Brazil actively use Mercado Pago (it reported 88 million monthly active users in Q2 2026), and it's on more than 55,000 e-commerce websites.
Alipay for Asia's Payment Processing
Alipay is a payment gateway that caters to China and Asia. Founded in 2004, it is China's largest online payment service, with over 1.3 billion active users and $17 trillion worth of processed transactions in 2020 alone.
Over 80 million merchants use it in their businesses, relying upon its "smart e-commerce, rapid digital transformation, and powerful data-driven marketing capabilities" to drive their e-commerce goals. It works for merchants using Alibaba and Taobao and supports external merchants such as Lenovo and CCTV.
Authorize.net's Credibility with Visa's Backing
Authorize.net, a subsidiary of Visa, was founded in 2004 and has since grown to become a trusted gateway for accepting various payment methods for e-commerce and online marketplace websites. These include debit and credit cards, eChecks, and other digital payment platforms like PayPal and Apple Pay.
It has served over 445,000 small businesses, processing more than 1 billion transactions every year, amounting to $149 billion worth of payments.
Its most-loved features are automatic recurring billing, advanced fraud detection, and customer information management. Through these functionalities, it has served over 445,000 small businesses, processing more than 1 billion transactions every year, which amounts to $149 billion worth of payments.
SecurePay, Australia's Payment Gateway
And Down Under, we have SecurePay. Founded in 2009, it is now trusted by more than 90,000 large and small businesses.
It's also a trusted choice for Australia's budding e-commerce industry, which recently saw 44% of online payments made with debit cards.
A Wide Variety of Options with Yclas' Payment Gateways
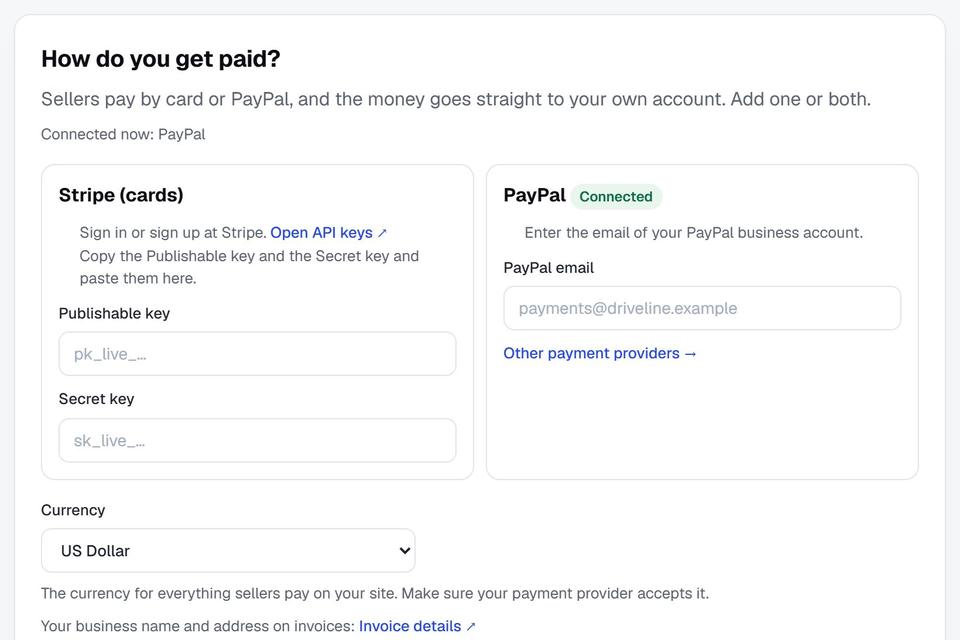
Yclas supports dozens of payment gateways, including these ten. Ready to add one to your online marketplace website?
Build your own online marketplace today.
What These Payment Gateways Cost in 2026: A Side-by-Side Comparison
Fees matter more than features once a marketplace starts taking real volume. The table below uses each provider's published standard rates for US merchants, checked in October 2026, and shows what a single $100 sale would cost. Negotiated, high-volume and country-specific pricing will differ, so check the provider's page for your own country before you choose.
| Gateway | Published standard rate | Cost on a $100 sale | Monthly fee |
|---|---|---|---|
| Stripe | 2.9% + $0.30 for US cards; manually keyed cards 3.4% + $0.30 | $3.20 | None |
| PayPal Checkout | 3.49% + $0.49; card processing 2.99% + $0.49; +1.50% for international payments | $3.98 (or $3.48 by card) | None |
| Authorize.net (all-in-one) | 2.9% + $0.30 | $3.20 | $25 |
| 2Checkout (now Verifone), 2Sell plan | 3.5% + $0.35 | $3.85 | None |
| BitPay (under $500k/month) | 2% + $0.25; 1.5% and 1% tiers at higher volume | $2.25 | None |
| Escrow.com | 2.6% up to $5,000, $50 minimum; +3.05% when the buyer pays by card or PayPal | $50 (the minimum) | None |
Published standard rates for US merchants, before any monthly fee. Escrow.com is left out: its $50 minimum would fill the scale. Sources are in the table above.
Show the numbers
| Gateway | Cost on a $100 sale | Notes |
|---|---|---|
| PayPal | $3.98 | 3.49% + $0.49; $3.48 when paid by card |
| 2Checkout | $3.85 | 3.5% + $0.35, 2Sell plan |
| Stripe | $3.20 | 2.9% + $0.30 for US cards |
| Authorize.net | $3.20 | 2.9% + $0.30, plus $25 a month |
| BitPay | $2.25 | 2% + $0.25 under $500k a month |
How to read these numbers
- Low-value listings and fees: for $5–$20 payments, such as featured-ad upgrades or posting fees, the fixed part of the fee matters most. PayPal's $0.49 is a larger share of a $5 payment than Stripe's $0.30.
- High-value items between users: escrow only makes sense for expensive items. On a $100 sale, Escrow.com's $50 minimum is half the price. On a $4,000 item, its 2.6% ($104) buys protection that a card payment doesn't give either party.
- International buyers: cross-border surcharges add up. On its standard US pricing, Stripe adds 1.5% for international cards and 1% when currency conversion is needed, and PayPal adds 1.50% for international transactions.
- Fixed monthly costs: Authorize.net's $25 monthly fee only pays off once you process a steady volume. Stripe, PayPal, 2Checkout and BitPay have no monthly fee and only charge when you get paid.
What else has changed since 2023
The two biggest gateways are much larger than when this article was written. Stripe says businesses on its platform processed $1.9 trillion in 2025, up 34%, and a February 2026 tender offer valued it at $159 billion. PayPal ended 2025 with 439 million active accounts and $1.79 trillion in payment volume. If you are considering Robokassa for a Russian-language marketplace, note that Visa and Mastercard suspended their operations in Russia in March 2022. Cards issued in Russia no longer work abroad, and foreign cards no longer work at Russian merchants, so a Russia-focused gateway cannot serve both audiences at once.
Stripe and PayPal for Marketplaces in 2026: Extra Fees, Seller Payouts and Card Security
This page also replaces our older posts on why to use Stripe for a marketplace, on why to use PayPal, on payment gateway best practices for classifieds sites, and on building a marketplace with Stripe Connect on Yclas.
Fees beyond the headline card rate
Other charges marketplace owners run into, from Stripe's pricing page and PayPal's US merchant fee page (standard US prices, checked October 2026):
| Item | Stripe | PayPal |
|---|---|---|
| Other payment methods | ACH Direct Debit 0.8%, capped at $5.00 ($4 per failed payment, $15 per disputed payment, per local payment methods pricing); stablecoin payments 1.5% of the transaction amount | Pay with Venmo: 3.49% + $0.49 |
| Currency conversion | +1% | 4.00% spread when a payment arrives in a different currency, 3.00% for other conversions |
| Disputes | $15 per dispute received + $15 if you respond manually (returned if you win) | $20.00 chargeback; $15.00 standard dispute fee |
| Faster payouts | Instant Payouts: 1.5% of the payout amount (Stripe support) | Instant transfer to your bank: 1.50%, $0.50 minimum |
Two details catch many owners out. Stripe refunds are free to issue, but Stripe does not return the processing fee of the original payment. And on small payments the fixed fee dominates: PayPal Checkout takes $0.84 (8.4%) of a $10 sale and about $0.66 (more than 13%) of a $5 featured-listing upgrade. That is why many marketplaces sell bundles (for example, 5 featured days) or monthly seller plans instead of many tiny payments.
Paying sellers with Stripe Connect
Stripe Connect pays your sellers. It has two pricing models:
- Stripe handles pricing. Stripe charges your sellers' processing fees directly, and your platform pays no account, payout or tax-reporting fees.
- You handle pricing. It costs $2 per monthly active account (a seller who received a payout that month) plus 0.25% + 25¢ per payout, and $2.99 per 1099 e-filed with the IRS (Stripe 1099). Cross-border payouts cost from 0.25%.
On Yclas, Stripe Connect is set up in Panel > Integrations > Stripe: add your Stripe secret and public keys, tick Activate Stripe Connect and set your Application fee %. How it works today:
- Sellers no longer need their own Stripe account to start. A seller who clicks connect gets a Stripe Express account and completes Stripe's hosted onboarding. No client ID is needed. The older client ID and redirect URL flow is now the optional Stripe Connect Legacy mode; its OAuth settings are under Settings > Connect > Onboarding options > OAuth, and in live mode the redirect URL must use HTTPS.
- Connecting before posting is optional. Enable "Make a connected Stripe account mandatory" if every seller must connect before posting an ad.
- Escrow flow: payouts are held for sellers who connect after you turn it on. The seller marks the order as shipped, optionally with a tracking code, and the payout is released when the buyer marks it as received. Orders not shipped within a set number of days can be canceled (the transfer is reversed), and you can add a fixed fee on top of the percentage.
- Different fees per membership plan, so sellers on a paid plan can pay a lower commission.
Yclas uses Stripe Checkout with destination charges: the buyer pays your platform account, the full amount is transferred to the seller, and your application fee comes back to you. With this charge type your platform balance pays the Stripe fees, refunds and chargebacks, so Stripe's "you handle pricing" Connect model applies.
Check your commission against the card rate. A seller makes ten $100 sales on US cards in a month and is paid once: card processing is 10 × $3.20 = $32.00, and the platform also pays $2 for the active account and about $2.67 on the $968 payout. Now take a $400 phone with a 3% commission: the fee is $12, but processing the charge at 2.9% + 30¢ costs about $11.90, which the platform pays, leaving about $0.10 before account and payout fees. Set your commission well above the card rate, use the escrow flow's fixed fee for low-priced items, and check one real test sale in your Stripe dashboard.
Calculator
One sale: what the seller gets and what you keep
Enter an item price, your commission and your payment provider's rate (Stripe's standard US card rate is 2.9% + $0.30).
Taxes, refunds, chargebacks and currency conversion are not included. More free tools →
Three ways to use PayPal on a marketplace
- Platform fees only. PayPal pays you for listing fees, featured ads or memberships, and you stay out of the money flow between users.
- Buyers pay sellers directly. Each seller adds their own PayPal account and a "Buy Now" button sends payment straight to them. Disputes and fees sit with the seller, but you cannot take a commission automatically. Yclas supports this as the "Buy Now button" option in its PayPal integration.
- Split payments through PayPal for Platforms. PayPal's platform product handles seller onboarding, risk and payouts and accepts PayPal, Venmo, Pay Later, cards, Apple Pay and Google Pay. There are no upfront or monthly fees, but rates are negotiated with PayPal's sales team, so expect an approval process.
PayPal's Trustpilot score is 1.4 out of 5 from more than 41,000 reviews, mostly about frozen accounts and disputes. Offer a second gateway so one account limitation cannot stop all sales.
Tax forms your sellers will ask about
In the US, payment platforms send Form 1099-K when a seller's payments for goods or services exceed $20,000 in more than 200 transactions in a year, according to the IRS (page reviewed 28 June 2026). All income must be reported whether or not a form arrives: worth saying in your seller FAQ.
Card security: PCI DSS v4.0.1
The PCI Security Standards Council retired PCI DSS v3.2.1 on 31 March 2024. Version 4.0 was replaced by v4.0.1, the only active version since v4.0 was retired on 31 December 2024, and the "future-dated" requirements became mandatory on 31 March 2025. The simplest way for a small marketplace to stay compliant is to never let card numbers touch its own server: use the gateway's hosted checkout or payment page and keep HTTPS on every page.
Finally, match the gateway to your country first: a local gateway (such as Mercado Pago in Latin America or Razorpay in India) often converts better because buyers recognize it.
Frequently Asked Questions
Can I Create My Own Payment Gateway?
Yes, it is possible to create your own payment gateway. However, it is a complex undertaking that requires technical expertise, regulatory compliance, and a significant investment of time and resources.
Here are the general steps involved in creating your own payment gateway.
- Research and Planning: Understand the payment industry, existing payment gateways, and the requirements for establishing a new one. Identify your target market, unique selling points, and revenue model.
- Obtain Necessary Licenses and Compliance: Research and comply with your target markets' legal and regulatory requirements. This may include obtaining licenses such as Payment Service Provider (PSP) licenses, adhering to data protection and security standards, and complying with anti-money laundering (AML) and know-your-customer (KYC) regulations.
- Technical Infrastructure: Build a robust and secure technical infrastructure to handle payment processing. This includes developing or integrating with payment APIs, ensuring data encryption, implementing fraud prevention measures, and establishing a reliable network and server infrastructure.
- Partner with Acquirers and Processors: Establish relationships with acquiring banks and payment processors to facilitate the movement of funds between customers, merchants, and banks. This typically involves negotiating agreements and integrating their services into your payment gateway.
- User Interface and Experience: Design and develop a user-friendly interface for both merchants and customers. This includes features such as payment forms, checkout flows, transaction history, reporting tools, and customer support.
- Security and Fraud Prevention: Implement robust security measures to protect sensitive customer information, prevent fraudulent activities, and ensure compliance with industry standards such as Payment Card Industry Data Security Standard (PCI DSS).
- Testing and Integration: Thoroughly test your payment gateway to ensure it functions smoothly across different platforms, browsers, and devices. Integrate with popular e-commerce platforms and shopping carts to expand your reach.
- Ongoing Maintenance and Support: Continuously monitor and maintain your payment gateway to ensure its stability, security, and compliance with evolving industry standards. Provide prompt customer support to address any issues or inquiries.
Creating your own payment gateway requires significant financial investment, so we recommend using an existing solution like Stripe or PayPal. Many entrepreneurs and businesses opt to partner with existing payment gateway providers.
Who Needs a Payment Gateway?
A payment gateway is vital for individuals and businesses engaging in online transactions, especially for businesses that require the ability to accept payments electronically. Here are some examples of who typically needs a payment gateway:
- E-commerce Businesses: Online retailers and businesses selling products or services through their websites. These websites rely on payment gateways to securely process customer payments. Whether it's a small boutique shop or a large-scale online marketplace, a payment gateway enables them to accept credit cards, debit cards, and other digital payments from customers.
- Service Providers: Professionals and service-based businesses such as consultants, freelancers, software developers, and subscription-based businesses. These businesses often use payment gateways to accept online payments for their services, set up recurring billing for subscriptions, and manage customer invoices.
- Nonprofit Organizations: Nonprofits often rely on donations and fundraising efforts to support their causes. Payment gateways enable them to accept online donations securely, providing various payment options to donors and simplifying the donation process.
- Travel and Hospitality Industry: Travel agencies, hotels, airlines, and other businesses in the travel and hospitality sector use payment gateways, primarily to accept online payments for bookings, reservations, and other travel-related services.
- Educational Institutions: Schools, colleges, and other educational institutions use payment gateways to facilitate online payments, specifically for tuition fees, course enrollments, and other educational services.
- Government Agencies: Government bodies and agencies often need to collect fees, taxes, fines, and other payments from citizens and businesses. Payment gateways offer a convenient and secure way to process these payments online.
- Online Marketplaces: Platforms that connect buyers and sellers, such as e-commerce marketplaces, classified websites, and peer-to-peer platforms, require payment gateways to handle the financial transactions between parties.
- Mobile Apps and In-App Purchases: Mobile app developers and businesses that offer mobile applications with in-app purchases or subscription services. These mobile providers rely on payment gateways to handle the payments seamlessly within the app.
- Event Organizers: Companies or individuals organizing conferences, concerts, sporting events, or other types of events. These organizers use payment gateways to sell event tickets and process registrations or bookings online.
What Risks Are There in Payment Gateways?
Like any online system that handles financial transactions, payment gateways come with certain risks. Here are some common risks associated with payment gateways to watch for:
- Security Breaches: Payment gateways can be vulnerable to hacking attempts or security breaches. Sometimes this can lead to unauthorized access to sensitive customer data, including credit card information.
- Data Theft: If a payment gateway is compromised, cybercriminals can potentially steal customer payment data, including credit card numbers, expiration dates, and security codes. This information can be used for fraudulent purposes, such as making unauthorized purchases or identity theft.
- Fraudulent Transactions: Payment gateways can be targeted by fraudsters who attempt to use stolen credit card information or employ other deceptive practices to make fraudulent transactions. If not properly detected and prevented, these transactions can result in financial losses for businesses. Watch for them, although they are usually minimal.
- Payment Disputes and Chargebacks: Disputes between customers and merchants can arise regarding the quality of goods or services provided. If customers are dissatisfied, they may initiate chargebacks, where they request a refund from their credit card company. Excessive chargebacks can lead to financial penalties and reputation damage for the merchant. It's important to have clear guidelines to fall back on.
- Compliance and Legal Issues: Payment gateways must comply with various regulations and standards, such as the Payment Card Industry Data Security Standard (PCI DSS). Non-compliance can result in financial penalties.
- System Downtime: Payment gateways need to ensure high availability and uptime. Any prolonged system downtime or technical issues can disrupt payment processing, resulting in a loss of revenue for businesses and customer dissatisfaction. It's rare to have any downtime.
- Integration Challenges: Integrating a payment gateway with a business's existing systems and processes can sometimes be complex. Inadequate integration can lead to errors, transaction failures, and inconvenience for customers. Most integrations today are fairly straightforward, though.
To mitigate these risks, payment gateways employ robust security measures like encryption, tokenization, two-factor authentication, and fraud detection systems. Businesses should also ensure they select reputable and reliable payment gateway providers, regularly update their systems, and stay informed about emerging security threats and best practices in the industry.
Thinking of starting a buy-and-sell site of your own? See our marketplace website builder, software for a second-hand marketplace and how to start an online marketplace.